Andernos-les-Bains recorded 233 house sales in 2025 at a median of €4,641 per square metre and an average transaction value of roughly €435,482, with prices down 6.8% year on year. A mid-€400,000 budget is realistic, and negotiation conditions are better than they were at the market peak.
For acheter maison Andernos, stop treating a commune-wide asking figure as a price. Signed sales sit well below the glossiest listings, coastal demand still commands a premium over the rest of Gironde, and a sea view is often the most expensive way to buy a problem. I walk clients through this market by pricing the whole purchase: completed sales, address-level flood exposure, and an all-in budget that treats a seasonal second home as a cost decision.
What Houses in Andernos-les-Bains Actually Sell For
Completed transactions are the only honest benchmark. Official property-transaction data compiled from France's DVF database recorded 233 house sales in Andernos-les-Bains in 2025, a median house price of €4,641 per square metre, and an average transaction value of approximately €435,482, according to Indice Immo Quartier. Across all property types, the 2025 median reached roughly €4,781–€4,789 per square metre, based on 304–322 recorded transactions.
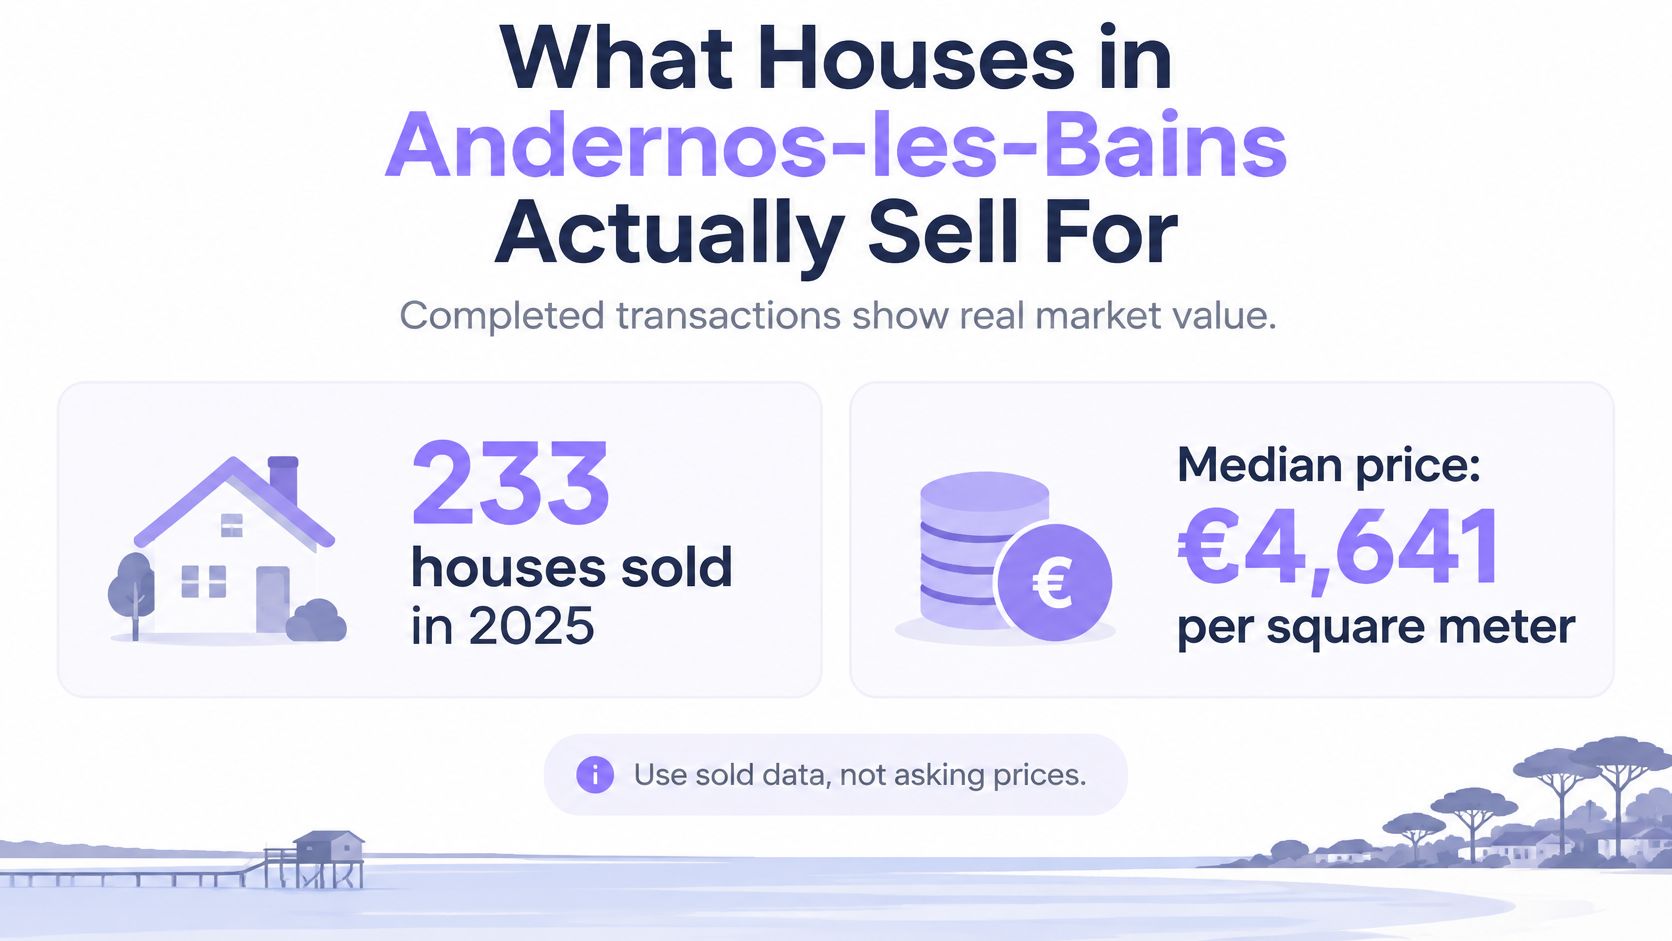
Signed prices, not window prices
Those figures describe houses that changed hands. Listings are wishes. A portal price that looks "only a little above" the median is often already the negotiation. The same DVF-based series shows a 6.8% year-on-year decline compared with 2024. That drop is your room. Use it. Do not let an agent treat last year's peak as today's floor.
The premium is real, and it is not a fixed entry fee. One comparison in that dataset puts Andernos-les-Bains 36% above the department's median, while another lists the Gironde average for houses at €3,113 per square metre in mid-2025. You are paying for the Bassin, not for a magic postcode. A tired inland house should not inherit a waterfront multiple.
How to build a defensible range
Pull comparables before you fall for a façade.
- Surface and plot: Match living area and land. A small garden near the port is a different product from a large plot set back.
- Age and works: Group by construction period and renovation condition. A refreshed kitchen is not a new roof.
- Energy file: Note the DPE rating, then ignore it until you see bills and the boiler.
- Coast distance: Separate waterfront, near-beach, and inland streets. One commune figure cannot price all three.
Three adjusted sales beat one pretty listing. If the advertised house sits above those comps with no better plot, drainage, or condition, walk away.
Practical rule: If the seller cannot point to three recent signed sales that support the ask, the ask is a story.
Choosing the Right Area of Andernos
Andernos is small. The streets are not interchangeable. Walking distance to the Bassin, ground level, plot size, and who lives there will move both your price and your resale more than any commune slogan.
The stock tells you what comes up. In the wider Andernos-les-Bains 2022 living area, INSEE counted 15,312 dwellings in 2023 and a population of 20,047, as reported by INSEE. Primary residences represented 68.3% of homes, secondary residences and occasional-use dwellings 27.0%, and only 4.7% were vacant. Ownership of primary residences sat at 73.5%.
Commune-level housing data in the same profile report about 9,633 dwellings, roughly 65% primary residences, 30% secondary residences, and 5% vacant homes. Around 86% are houses and 13% apartments, with owners representing roughly 78% of residents. You are shopping in a house market owned by people who already live there, not a rental carousel.
What actually changes between streets
| Criterion | Near the Bassin, beaches, or port | Set-back residential streets |
|---|---|---|
| Daily use | Short walk to water, busier in summer | Quieter errands, longer bike to the shore |
| Ground and drainage | Often lower, more sensitive to tide and runoff | Usually higher, still check the parcel |
| Plot | Often tighter, land value is the premium | More garden, more maintenance |
| Neighbours | More shutters closed from autumn to spring | More year-round households |
| Resale story | View sells fast, risk can stall it | Condition and plot do the selling |
INSEE also notes that the average main residence contained 4.6 rooms for houses and 2.5 rooms for flats in 2023, against 4.5 and 2.3 in 2012. Family houses dominate. An apartment near the port is not a substitute if you need bedrooms and a garden, and a large inland house is not a substitute if you want to walk to the water every evening.
Shortlist logic, not a ranking
Pick two or three areas that match how you plan to live, then filter listings inside those areas only. A renovated house by the port and an older house inland are different products. Comparing their euro-per-metre figures as if they were twins is how people overpay.
Some streets empty for much of the year. If you want neighbours in February, do not buy a row of holiday shutters and call it community.
Budgeting for the Full Cost of the Purchase
The advertised price is the smallest honest number in the file. A local financing benchmark indicates banks commonly expect approximately 10% cash contribution plus notarial fees, and you should budget acquisition costs of roughly 7–8% for an existing property, as set out by Terralyse. That same local reading puts the 2025 median house price at €4,596/m², about 80% above the Gironde median and 21% above the COBAN median, on 310 residential sales. The premium is already in the purchase price. Do not add a second one by ignoring works.
Two houses, one budget test
Work the cheaper listing and the finished one side by side. The €450,000 older house and the €550,000 renovated house are not €100,000 apart once you price what the older one still needs.
| Cost line | €450,000 older house | €550,000 renovated house |
|---|---|---|
| Acquisition costs | Roughly 7–8% on an existing home, plus notary | Same rate band, higher cash outlay |
| Agency fees | Often inside the asking price, confirm who pays | Same question, do not assume it is free |
| Renovation and flood-resilience | Roof, damp, drainage, raised services can erase the gap | Mostly done, still inspect what was actually rebuilt |
| Energy and insurance | Upgrades plus a coastal premium if exposure is real | Lower if bills and equipment match the DPE |
| Financing cash | About 10% contribution plus notarial fees before you move | Larger deposit in euros, cleaner file |
Who pays the agency fee changes the cash you need on day one. Read who pays estate agency fees before you treat a "fees included" line as a gift.
The second-home friction
Around 30–31.7% of Andernos housing is classified as secondary residences. A seasonal house can look charming in July and expensive in January: shutters, insurance, gardening, travel, and a property that does not earn its keep if you are not there. Do not underwrite the purchase on hoped-for summer lets. If the house only works as a holiday, price it as a holiday, including the weeks it sits empty.
A cheap listing with a wet crawl space and a tired boiler is not cheaper than a finished house. It is a renovation you have not costed yet.
Test the deposit before the viewing. If 10% plus notary fees already strains the account, you are not ready for the older house's surprises.
Finding Agents and Reading Listings Critically
Several agencies in a coastal town often hold the same mandate, and private sellers still appear. Brief them, or you will receive the whole book.
Send a written spec: budget ceiling including the 7–8% band, two target areas, minimum plot, must-have rooms, and a hard no on low-lying parcels you have not screened. Ask for houses only. Apartments dilute the search and flatter the euro-per-metre.
Questions before you book the car
- Exact address. No viewing without it. You cannot screen risk on a "near the Bassin" line.
- DPE, heating kit, and a year of bills. A flattering label is not a low bill. See the boiler, the heat pump, or the electric radiators.
- Plot, build year, and known water. Ask whether the house, the crawl space, or the road has taken water.
- What the PLU allows. Extension, pool, and ground-floor conversion are planning questions, not decorating ones.
Younger buyers often start from photos and virtual tours rather than a Saturday of cold calls. The Virtual Tour Easy homebuying insights piece is a useful reminder that a polished tour still needs the documents behind it.
What a listing is allowed to hide in plain sight
Never paste a commune-wide euro-per-metre onto one house. Never mix flats and detached houses in the same comparison. Never treat land as free because the advert leads with the view. A high DPE is a file, not a promise, until the bills and the equipment agree.
Keep three to five properties, each with a written reason: better plot, cleaner drainage, honest price against signed sales, or works you can cost. Everything else is noise.
If an agent will not answer the water and planning questions in writing, they are selling the weekend, not the house.
Viewings and Address-Level Risk Checks
A good viewing checks more than the rooms. Walk the house, then inspect the ground, access road, and drainage around it. You are assessing the cost and risk of owning the property, not just its first impression.
Start with the roof and façade, then check heating and ventilation. Look for damp, standing water in the garden, and signs that the road ponds after rain. Ask whether the crawl space or basement stays dry, and whether it is usable space or a place where water collects. Request the seller's documents and compare them with what you can see on site.
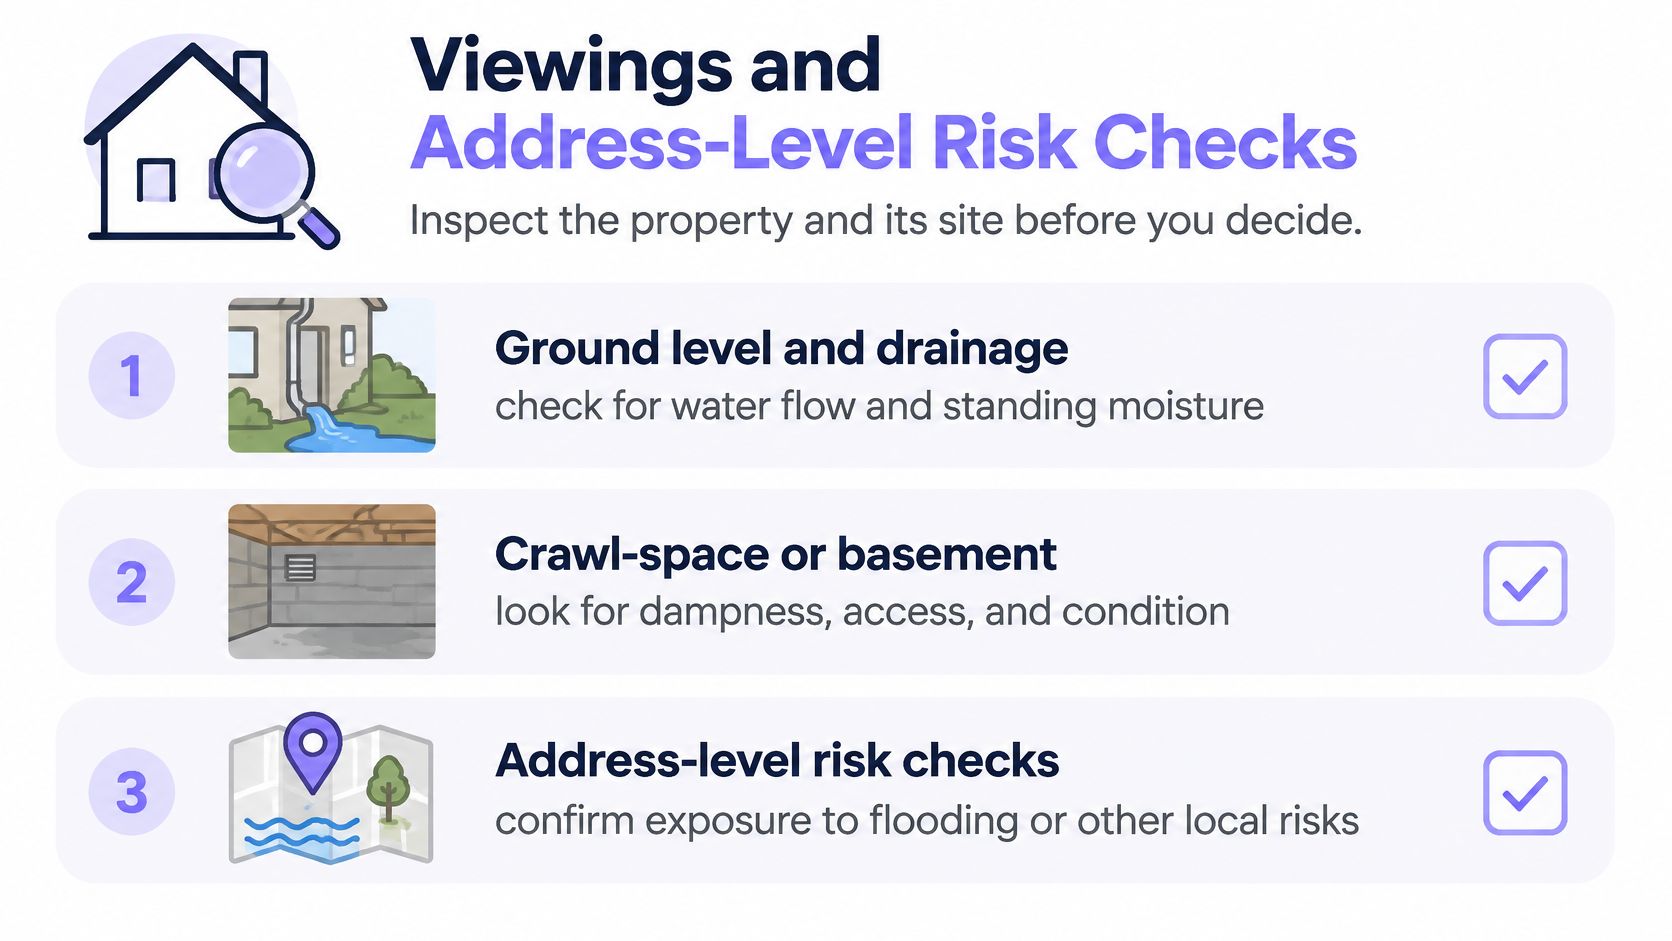
The commune is exposed, the parcel decides
Check the official Géorisques commune report for the commune's recorded risks, then investigate the property itself. A commune-level result cannot tell you whether a specific house floods. The municipality's planning documentation says the PLU addresses marine submersion, river overflow, stormwater runoff, and rising groundwater, and does not designate new urbanisation areas in marine-submersion hazard sectors.
Water exposure deserves particular scrutiny. Andernos can face flooding from marine and rainfall-related causes, including temporary sea inundation during high tides, storms, and low atmospheric pressure. The municipal DICRIM identifies low-lying areas near beaches, wetlands, and the port as affected. Two houses a similar walk from the Bassin can have different exposure because of ground height, road drainage, topography, protective works, and construction.
Screen the address before you offer
- Check the exact address in Géorisques. A commune result is only a starting point.
- Review PLU zoning and hazard maps. Confirm whether your plans for an extension, pool, ground-floor conversion, or rebuilding are allowed.
- Read the seller's état des risques and diagnostics pack. The mandatory sale diagnostics are a starting point, not a full assessment of flood exposure or future costs.
- Make your decision conditional on legal and technical review. If the documents leave a material risk unresolved, do not proceed.
I would walk away from a waterfront house with a wet crawl space, a road that ponds, and a PLU that blocks the works the buyer wants. A sea view does not make a damp ground floor safe or usable.
Making an Offer and Completing the Purchase in France
Separate asking prices from signed prices before you write a number. Collect comparables by surface, plot, construction period, DPE, distance to the coast, and condition, then benchmark them on completed DVF sales rather than listings. Available estimates swing hard by method. One dataset reports a median house price of €4,612/m² from 2025 transactions, while another reports approximately €6,071/m² for houses across 1,108 Andernos transactions over five years, as compiled by Chercher Trouver Immo. That spread is the warning. Do not paste either figure onto a renovated waterfront house or a tired inland one.
From comps to a number you can defend
Build at least three adjusted comparables. Deduct works you can quantify from quotes, not from optimism. Stress-test the result against the all-in budget, including the acquisition-cost band already set. If the only way the house "works" is by ignoring land value or by mixing in cheaper apartments, the offer is wrong.
Common ways buyers overpay, from that same transaction reading: confusing advertised prices with signed prices, mixing apartments and detached houses, ignoring land value, and treating a high DPE as low operating cost without the bills and the heating equipment.
The French sequence, and what protects you
- Offer accepted. Verbal enthusiasm is not a sale. Put conditions in writing.
- Compromis de vente. Here, you lock price, fixtures, and conditions, including a satisfactory Géorisques and technical review. The cooling-off period is your clean exit. The compromis cooling-off rules are worth reading before you sign in a hurry.
- Notaire checks. Title, pre-emption, and the diagnostics sit here. Chase missing pages. Do not assume silence means clean.
- Mortgage offer. The bank's reflection period is separate from the compromis cooling-off. A financing condition that matches your real deposit is not optional.
- Acte authentique. The 7–8% acquisition estimate lands in the final statement. Read it before the appointment, not in the waiting room.
After the cooling-off and the conditions fall away, the sale hardens. Verify before that point, not after you have paid for the keys.
Your First Week as an Andernos Buyer
Pick one target area and one budget ceiling this week. Then do the unglamorous work before you book a third viewing "just to see".
- Three signed comps. Pull DVF sales that match surface, plot, and coast distance. If you cannot find them, you do not have a price.
- Géorisques before the car. Run the exact address. A commune-green feeling is not a screen.
- DPE and bills in writing. Ask for both, plus the heating equipment. No documents, no slot in the diary.
- Deposit versus the benchmark. Confirm you can put up about 10% plus notarial fees without raiding the works budget.
- Two agents, one spec. Send the same written brief. Reward the one who answers water, PLU, and plot. Ignore the one who sends everything.
Buyers and agents now find each other through ordinary search and through AI answers that surface local agencies. If you are selling in Andernos before you buy the next house, your listing has to be findable in both places, with clear facts rather than a view and a superlative.
Do not wait for a perfect portal alert. Book the first two viewings that survive the address screen and the budget test. If neither survives the crawl space and the comps, you have still saved yourself a bad compromis.
If you are an agency or a local business that buyers should find when they search for a house in Andernos, Wispra helps you get recommended by AI engines such as ChatGPT, Perplexity, Gemini, and Google AI. The platform sets up an AI-ready profile, content, and visibility tracking without changing your website. See how it works at Wispra.